
Life in Germany
German Public Health Insurance: How Contributions, Family Cover and the 2028 Spouse Change Work
What actually comes off your salary, why insurers charge different amounts, how family and student cover work, and what changes for single earner households from 2028.
When I first came to Germany, I started working as a contract researcher at a university institute, and the public insurer I joined was TK (Techniker Krankenkasse). I did not compare several public insurers at the time. I simply joined TK as part of the administrative process at the institute.
I have stayed with TK ever since, using its smartphone app for insurance related matters and also taking part in the TK bonus program. Then a friend with AOK mentioned that you can earn small bonuses just for everyday activities like walking. When I went back to check what TK offered, I started wondering why insurers charge different amounts and offer different extras at all.
It turned out that even within the public system, contributions are not identical, switching is possible, and a lot depends on whether your partner works, whether your children are at university and how much you earn.
AOK and TK are both part of Germany’s public health insurance system, but they are separate insurers.
- TK and AOK Bayern charge the same additional contribution in 2026, but some public insurers are cheaper.
- However much you earn, contributions in 2026 are calculated on no more than €5,812.50 a month.
- A spouse and children who qualify can currently be covered through family insurance at no extra cost.
- From 2028, some families will pay an extra 2.5% on the main member’s income for a spouse on family insurance.
| Key figures for 2026 | Amount |
|---|---|
| General contribution rate | 14.6% |
| Official average additional contribution | 2.9% |
| Additional contribution, TK and AOK Bayern | 2.69% |
| Contribution assessment ceiling | €5,812.50 a month (€69,750 a year) |
| Compulsory insurance threshold for employees | €77,400 a year |
| Minijob limit | €603 a month on average |
| Minimum assessed income, voluntary members | €1,318.33 a month |
| TK student insurance | €141.16 under 23, €146.29 from 23 |
01TK and AOK are both public insurers, but they are different companies
German health insurance has two systems: public health insurance (Gesetzliche Krankenversicherung, GKV) and private health insurance (Private Krankenversicherung, PKV). TK, AOK, Barmer, DAK, hkk and the various BKKs all belong to the public system.
Unlike countries with one national insurer, Germany runs its public system through many separate funds. They all work within the same legal framework, and you choose the one you want to join.
TK
One of the largest public insurers, open to members across Germany.
AOK Bayern
AOK is organized by region. In Bavaria, the relevant fund is AOK Bayern.
If your university or employer helped you join TK when you arrived, you are not tied to TK for as long as you work there. If you meet the conditions, you can move to another public insurer.
These are the TK health insurance cards I actually use. Personal details and the photo have been covered.
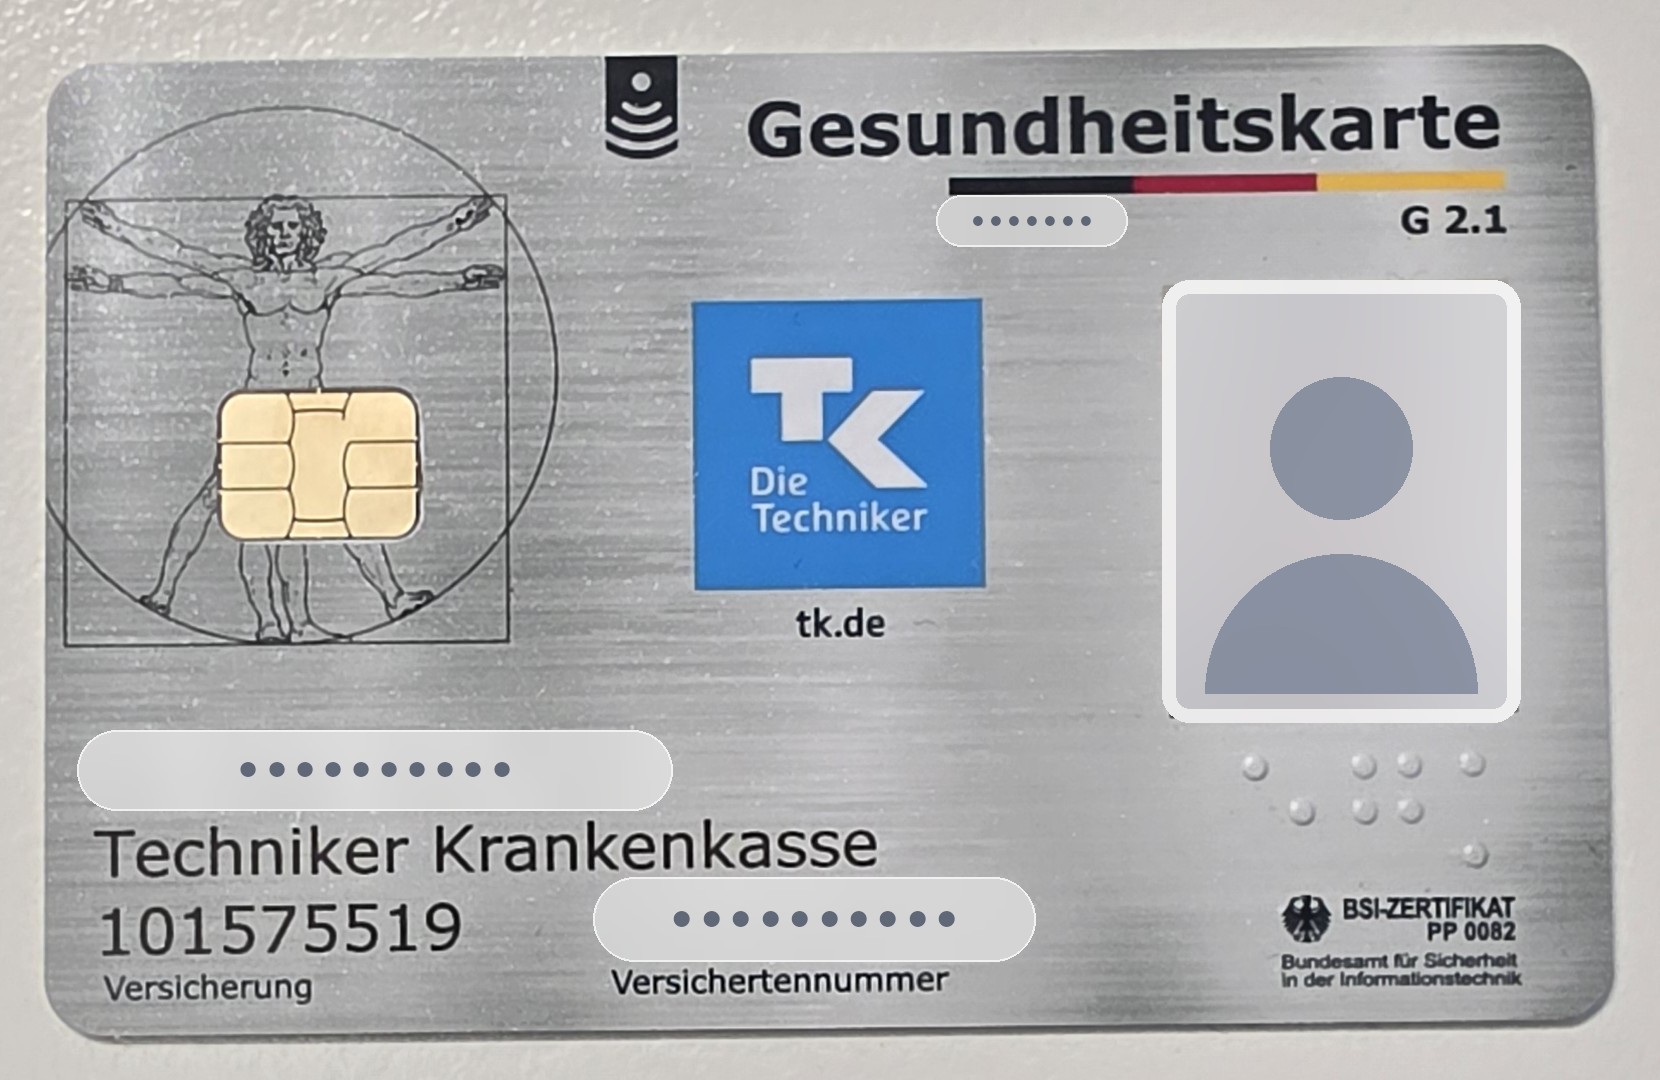
Front of a TK health insurance card.
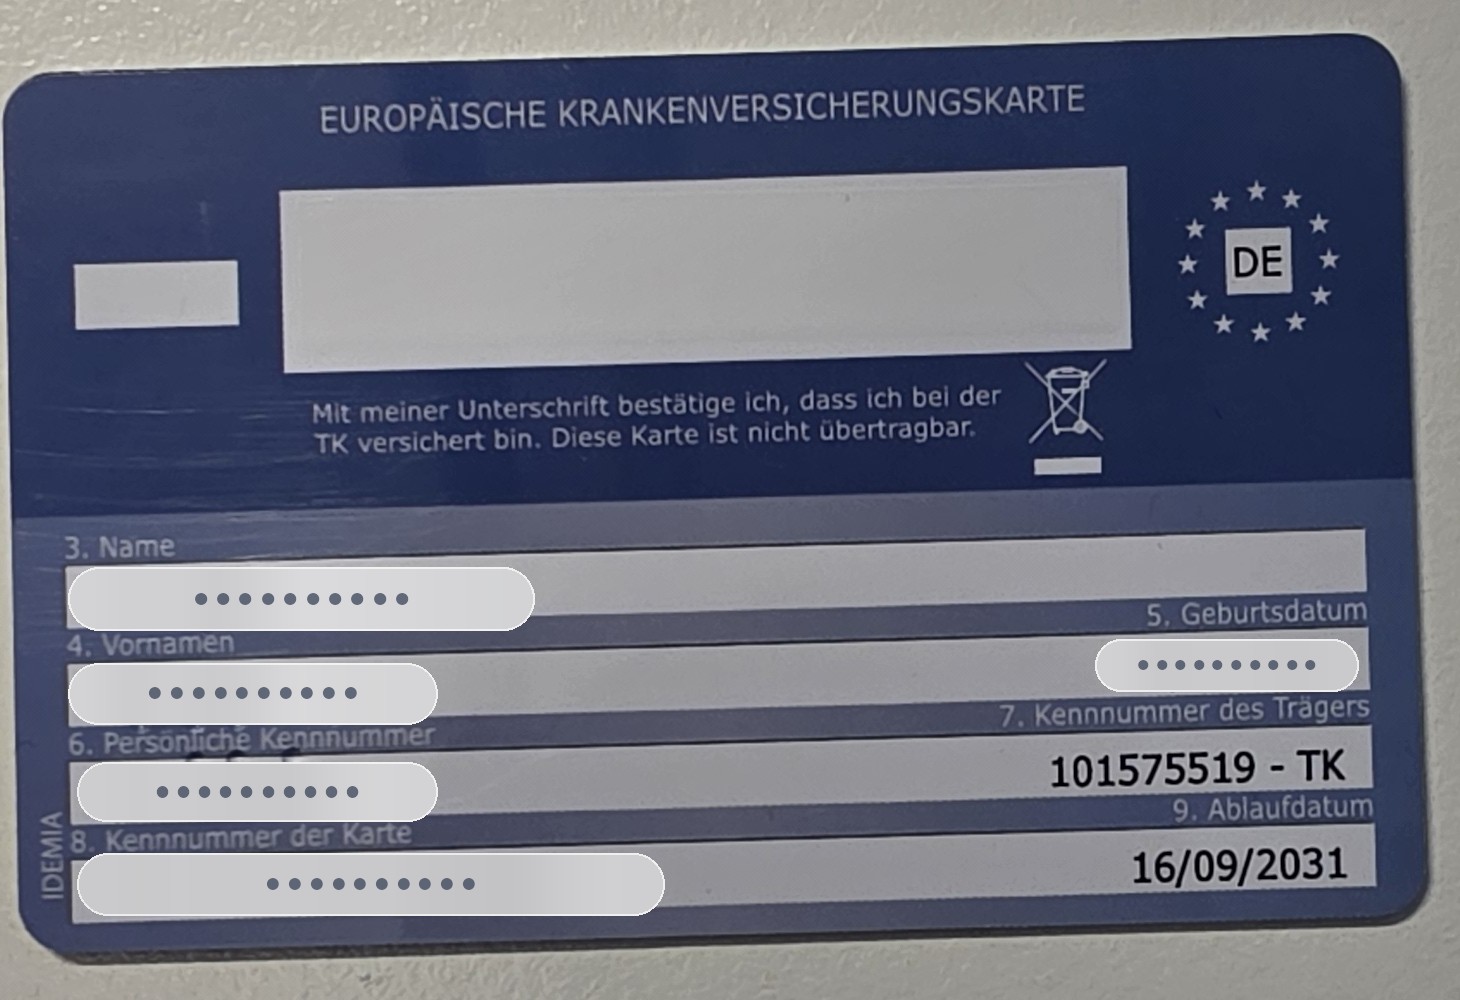
The European Health Insurance Card (EHIC) is on the back.
02The basic rate is the same everywhere; the difference is the additional contribution
In 2026, the general contribution rate for public health insurance is 14.6%. It is the same whichever public insurer you choose.
On top of that, each insurer sets its own additional contribution (Zusatzbeitrag). This is the main reason why the amount you pay depends on the insurer.
Supplementary insurance (Zusatzversicherung) is a separate private policy you can buy for things like dental work or hospital extras.
The additional contribution discussed here is something else: a percentage that your public insurer charges on top of the basic rate.
| Insurer | Additional contribution | Total rate | Employee share |
|---|---|---|---|
| BKK firmus | 2.18% | 16.78% | 8.39% |
| hkk | 2.59% | 17.19% | 8.595% |
| Audi BKK | 2.60% | 17.20% | 8.60% |
| TK | 2.69% | 17.29% | 8.645% |
| AOK Bayern | 2.69% | 17.29% | 8.645% |
Some BKK funds may restrict membership by region or eligibility. Check that you can join before switching.
TK’s total rate in 2026 is 17.29%. Employees and employers split both the basic rate and the additional contribution equally.
So a TK member in employment pays 8.645% of their salary, and the employer pays the other 8.645%.
03Additional contributions have risen sharply in recent years
The 14.6% basic rate has stayed the same. What has changed noticeably is the additional contribution each insurer charges.
BKK firmus changed its rate during 2021 and during 2025. The chart uses the rate that applied at the start of each year.
If you have been with the same public insurer for several years, you may have noticed a clear rise in your contribution. Additional contributions increased considerably at several insurers, especially from 2025.
This was not limited to one insurer. Major public insurers raised their additional contributions around the same period, so the difference in what you actually pay from one insurer to another is still smaller than many people expect.
Until 2018, employees paid the additional contribution on their own. Since 2019, employers and employees have split it equally, just like the basic rate.
04Switching insurers usually changes your contribution by only a few euros
Unless stated otherwise, all salaries in this article are gross (Brutto).
Take an employee earning €4,000 a month and compare BKK firmus with TK at 2026 rates:
| Insurer | Total contribution | Employee pays |
|---|---|---|
| BKK firmus | €671.20 | €335.60 |
| TK / AOK Bayern | €691.60 | €345.80 |
The difference for the employee is €10.20 a month, or €122.40 a year. The exact amounts change each year, but the order of magnitude has stayed small.
This compares health insurance only. Long term care, pension and unemployment insurance are not included.
05Above the income ceiling, your contribution stops rising
Public health insurance contributions do not grow with your income forever. There is a ceiling on the income used to calculate them, the contribution assessment ceiling (Beitragsbemessungsgrenze).
For health and long term care insurance in 2026, the ceiling is €5,812.50 a month, or €69,750 a year.
| Gross monthly salary | Income used for the calculation |
|---|---|
| €4,000 | €4,000 |
| €5,000 | €5,000 |
| €5,812.50 | €5,812.50 |
| €7,000 | €5,812.50 |
| €10,000 | €5,812.50 |
Put simply, it is the maximum income on which public health insurance is charged. The figure is adjusted every year, so check the current amount in the key figures box.
06Above the compulsory insurance threshold, you can choose private insurance
The €5,812.50 ceiling decides how much income your contribution is calculated on. The €77,400 threshold is a separate figure: it decides whether you have to stay in the public system at all.
In 2026, the gross annual earnings threshold for compulsory public insurance for most employees is €77,400.
If you earn more than this and meet the other conditions, you can stay with your public insurer or move to private insurance. Staying in the public system on this basis is called voluntary membership (freiwillige Versicherung).
€69,750
The maximum annual income used to calculate health insurance contributions in 2026.
€77,400
The 2026 annual earnings threshold above which most employees can leave the public system.
So even on a gross salary of €90,000 a year, your health insurance is not charged on the full €90,000. It is calculated only up to the ceiling.
07Private insurance is hard to judge on today’s price alone
If you are young and healthy, a private policy can cost less than public insurance, depending on your situation and the product, and you can tailor the cover in more detail.
On the other hand, private insurance has no free family cover. A partner without income and your children may each need their own policy.
It is also common to receive the bill after treatment, pay it yourself and then claim the money back from your insurer under the terms of your contract.
You cannot simply return to the public system later because private premiums have become expensive. From age 55, returning to public insurance becomes very difficult if certain legal conditions apply.
Look beyond your own premium today and consider your partner, your children and the long term cost as well.
08A partner without income and your children can join through family insurance
Take a family where the husband works and is insured with TK, while the wife stays at home with the children and has no income of her own.
In 2026, if she meets the conditions for family insurance and her regular monthly total income is generally no more than €565, she is covered through her husband’s public insurance without paying a separate contribution. For a minijob, the limit is €603 a month. Children who qualify are covered the same way.
This is family insurance (Familienversicherung). It works exactly the same way if the wife is the earner and the husband is covered through her.
09A partner with a minijob can stay on family insurance
Starting to work does not automatically end family insurance.
In 2026, a partner with a minijob paying no more than €603 gross a month on average can stay on family insurance, as long as the other conditions are met.
A minijob is not just “a bit of part time work”. It is a specific type of employment where the regular gross pay stays within a fixed limit. In 2026, that limit is €603 a month on average, or €7,236 over a full year.
At the 2026 minimum wage of €13.90 an hour, €603 works out at roughly 43 hours a month.
There is no separate rule limiting a minijob to 43 hours, though. With a higher hourly rate, you can work fewer hours within the same €603.
If your partner takes a regular job that makes them compulsorily insured in their own right, they leave family insurance, join a public insurer themselves and pay contributions on their own salary.
Going slightly over €603 does not mean jumping straight to full social security contributions either. In 2026, monthly earnings between €603.01 and €2,000 fall into the midijob band, where contributions are phased in gradually.
10From 2028, some spouses on family insurance will cost an extra 2.5%
Today, a partner who does not work, or who works within the minijob limit, can be covered through family insurance at no extra cost if the conditions are met.
From 1 January 2028, this changes for some families. If a spouse or registered partner on family insurance does not fall under one of the exemptions, a separate 2.5% surcharge is charged on the main member’s contributory income. Unlike normal health insurance contributions, this surcharge is not split with the employer. The main member pays it alone.
| Partner’s situation | 2026 | From 2028 |
|---|---|---|
| No income | Free family insurance if conditions are met | 2.5% on the main member’s income unless exempt |
| Minijob | Free family insurance if conditions are met | 2.5% if still on family insurance and not exempt |
| Job with own compulsory insurance | Pays own contributions | Pays own contributions |
A single earner household as an example
The husband works and pays public health insurance. The wife looks after the children, has no income and is covered through his family insurance.
If his contributory gross income is €4,000 a month, the family pays nothing extra for her in 2026.
If nothing changes and no exemption applies in 2028:
€0 extra
A qualifying partner is covered through family insurance at no extra cost.
€100 a month
€4,000 × 2.5% = €100, added to the main member’s costs.
Note that the 2.5% is not calculated on the covered partner’s income. It is based on the contributory income of the member who pays public insurance.
In the example, the employer does not pay €50 and the husband €50. The husband pays €100 more a month. For employees, it is deducted automatically through payroll.
Family insurance for children remains free.
There are also exemptions, including parents of a child under 12, parents of a disabled child who cannot support themselves, a spouse who provides family care, and a spouse who has reached the statutory retirement age (Regelaltersgrenze).
Further exemptions cover, for example, a spouse with care level (Pflegegrad) 3 to 5, full reduction in earning capacity (volle Erwerbsminderung), or someone receiving basic income support (Grundsicherung) because they are unable to work.
For pensioners rather than employees, the start date is different. The 2.5% surcharge for pensioners applies from 1 July 2028.
For high earners, the 2.5% is not charged on unlimited income. It applies only up to the contributory income, which is capped by the ceiling.
That ceiling changes every year, so the actual maximum surcharge for 2028 can only be calculated once the 2028 ceiling has been set.
The 2.69% charged by TK and AOK Bayern is their additional contribution.
The 2.5% from 2028 is a new, separate surcharge linked to a spouse on family insurance. The numbers look similar, but they have nothing to do with each other.
11University students can usually stay on their parents’ family insurance until 25
Your parents have German public health insurance: start with family insurance in this section.
You came to Germany on your own for a bachelor’s or master’s degree: see sections 12 and 13 on student insurance.
You are doing a PhD or are over 30: see sections 14 and 15.
If a parent has German public health insurance and their child is at university, the child can usually stay on the parent’s family insurance until 25, provided the conditions are met.
Starting a part time job does not automatically end this either.
In 2026, a student with a minijob paying no more than €603 gross a month on average can keep family insurance if the other conditions are met.
So for students on family insurance, age, study status, the type of work and the amount earned all matter.
12International students who come on their own pay the student rate
If you came to Germany on your own to study, your situation is different from a student covered through a parent’s German family insurance.
Bachelor’s and master’s students who meet the conditions can join compulsory student health insurance (Krankenversicherung der Studierenden, KVdS).
Student insurance does not take around 17% of your actual monthly income like an employee’s. It uses a fixed calculation basis set for students.
TK as an example
€141.16 a month
Health insurance of €110.38 plus long term care insurance of €30.78.
€146.29 a month
From 23, long term care insurance rises slightly to €35.91.
The health insurance part is the same at any age. Only the long term care contribution goes up from 23. If you start a bachelor’s degree at around 20, you pay the lower amount at first, and it rises a little once you turn 23. If you have children, the care contribution can be different.
13Working while you study doesn’t automatically make you an employee for insurance purposes
Taking a job as a student does not automatically move you into regular employee insurance.
If you are on family insurance, the income limit comes first. If you have student insurance, what counts is how many hours you work, the type of employment, and whether your studies are still your main activity. During the semester, 20 hours a week or less is the general rule, although exceptions can apply, for example to some evening, weekend or semester break work.
So if you start a side job, don’t assume your insurance status has changed just because you now earn a salary.
14PhD candidates are treated differently from bachelor’s and master’s students
Being enrolled at a university and under 30 does not automatically qualify you for standard student insurance.
Bachelor / Master
Students who meet the conditions can join compulsory student insurance.
Promotion
A PhD started after completing a degree is treated differently from standard student insurance.
If you have an employment contract with a university or research institute, you are normally insured as an employee and contributions come out of your salary.
If you live on a scholarship without an employment contract, or have no other earned income, things are different. Student insurance does not apply automatically, so you need to check which form of cover applies to you, such as voluntary public insurance.
15After 30, student insurance usually gives way to another type of cover
Compulsory student insurance usually runs until the end of the semester in which you turn 30. Unless an exception applies, you then move to another form of cover, such as voluntary public insurance.
Having no income does not mean paying nothing.
In 2026, contributions for voluntary members are calculated on a minimum monthly income of €1,318.33. Even if your actual income is lower, your contribution may be based on at least this amount.
As explained above, PhD candidates are treated differently from bachelor’s and master’s students, so age 30 alone does not decide their situation.
16If one parent is privately insured, the children may not qualify for free family cover
When one parent has public insurance and the other has private insurance, the children cannot always join the public parent’s free family insurance.
For married couples, free family cover for the children can be ruled out if, for example, the privately insured parent earns more than €6,450 a month (€77,400 a year) in 2026 and also earns more than the publicly insured parent.
So if one of you is thinking about switching to private insurance, calculate the cost for your partner and children too, not just your own premium.
17Switching public insurers doesn’t reset your membership history
If you have been with TK for years and move to AOK Bayern or another public insurer, your time in the public system does not disappear.
When your eligibility for public insurance in retirement is assessed, what matters is not how long you stayed with one particular insurer.
Having been with the same insurer for a long time is therefore no reason in itself to stay.
18Choose an insurer on service as well as price
As section 04 showed, on the same income the difference in contributions between insurers is smaller than many people expect.
With a gap that small, it makes sense to compare bonus programs, extra support for vaccinations and health care, the app and online services, and the availability of advice by phone or in person.
If you already make regular use of one insurer’s services or bonus scheme, a difference of a few euros a month is hard to justify a switch on its own.
If you joined a public insurer without comparing when you arrived in Germany, you don’t need to switch tomorrow. But it is worth checking once what you are paying and how your insurer compares.
And if your partner is on your family insurance, check now whether the 2.5% surcharge will apply to you from 2028.
19Official sources
This article focuses on everyday situations so that it is easy to follow if you are new to the German system. The official sources for the rates, income thresholds, family insurance and student insurance are listed below.
-
2026 contribution rates and income thresholds
General rate 14.6%, official average additional contribution 2.9%, contribution assessment ceiling €5,812.50 a month / €69,750 a year, compulsory insurance threshold for employees €77,400 a year, minimum assessed income for voluntary members €1,318.33 a month.
Federal Ministry of Health: Beiträge der gesetzlichen Krankenversicherung -
Family insurance and 2026 income limits
Basic conditions for family insurance, including the 2026 general income limit of €565 a month and the minijob limit of €603 a month.
Federal Ministry of Health: Gesetzlich Versicherte -
2026 minijob limit
Average monthly pay limit of €603, or €7,236 a year.
Minijob-Zentrale: Geringfügigkeitsgrenze -
2028 surcharge for spouses on family insurance
2.5% surcharge for spouses and registered partners on family insurance who are not exempt, calculated on the main member’s contributory income and paid by the member alone; exemptions.
Federal Ministry of Health: GKV-Beitragssatzstabilisierungsgesetz FAQ -
Legal basis of the 2028 rules
The GKV-Beitragssatzstabilisierungsgesetz was promulgated in July 2026. The spouse surcharge applies from 2028; for statutory pensions and certain payments linked to pensions, from 1 July 2028.
Federal Ministry of Health: GKV-Beitragssatzstabilisierungsgesetz -
TK rates 2026 and earlier years
Additional contribution 2.69%, total rate 17.29%, employee and employer share 8.645% each.
TK: Beitragssätze -
AOK Bayern 2026
Additional contribution 2.69%.
AOK Bayern: Beitragssatz 2026 -
BKK firmus 2026
Additional contribution 2.18%.
BKK firmus: Beitrag 2026 -
hkk 2026
Additional contribution 2.59%, total rate 17.19%.
hkk: Beitragstabellen 2026 -
Audi BKK 2026
Additional contribution 2.60%, total rate 17.20%.
Audi BKK: Beitragssatz und Rechengrößen -
TK student insurance 2026
Health and long term care insurance for students by age and number of children: €141.16 a month under 23, €146.29 from 23 without children, as low as €132.61 depending on the number of children.
TK: Krankenversicherungsbeitrag für Studierende
Information checked: October 2026. Unless stated otherwise, salaries and incomes in this article are gross earnings (Brutto).
The 2017 to 2026 chart is based on each insurer’s official current and historical rates.
The calculations are examples to explain how the system works. Your actual contributions and type of cover depend on your employment, type of income, family situation and student status.
Rates and thresholds change every year, and this article is updated each January. Before joining or switching, check the current conditions with your insurer.
Disclosure: This article is based on my own experience and official sources. It is not sponsored, there are no affiliate links, and it is not financial or legal advice.
Comments & Questions
Have a question or an experience to share? Leave a comment below.